

What happens when mortgage rates finally pick a lane, and it’s the lane heading up? Denver buyers just found out.
The 30-year fixed rate climbed every week in September and peaked near 7.5% by month’s end. Then the Federal Reserve raised its benchmark rate for the first time since July 2023.
Here’s the twist. September’s numbers don’t fully show that jolt yet. Most September closings went under contract in August, when rates hovered around 6.7%.
Closings hit a September low
Even before the rate spike landed, buyers tapped the brakes.
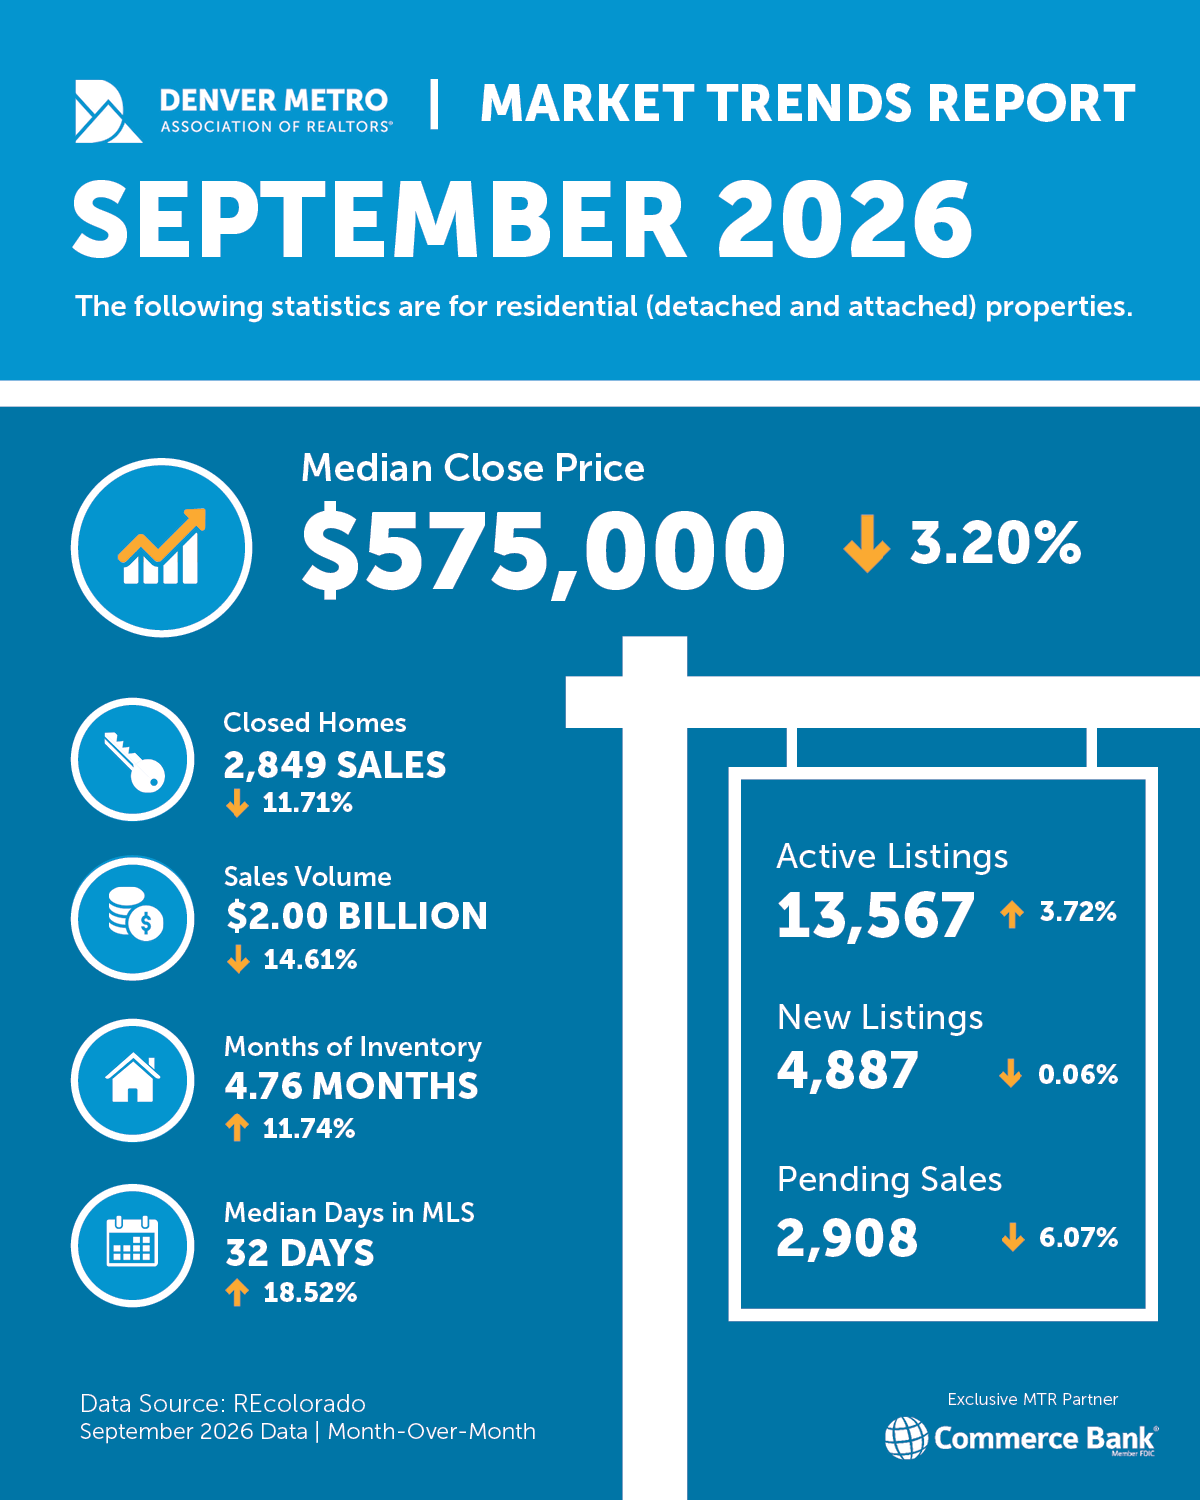
The Denver Metro Association of Realtors September report says closed sales dropped 12% from August and 21% from last September, landing at 2,849.
That’s the weakest September in records stretching back to the peak of the 2008 recession.
Pending sales offer the first real read on how buyers handled higher rates. They slipped 6% to 2,908.
That’s a step back, not a stampede.
Still, October and November closings could come in softer. Year-to-date, closings trail 2025 by 5%, and that gap keeps widening.
Buyers have more room to negotiate
Now for the good news. Denver closed September with 13,567 active listings and 4.76 months of inventory. More homes mean more choices. More choices mean more bargaining power.
Condos and townhomes tip the scales even further. That segment logged 7.21 months of inventory, and its median close price fell 6% year over year to $365,500.
But home prices? They haven’t cratered.
The year-to-date median close price for detached homes sits at $650,000, matching each of the past two years.
“As October begins, the fourth quarter tends to reward buyers who keep moving while others wait for a fresh start after the New Year,” said Amanda Snitker, chair of the DMAR Market Trends Committee.
“Buyers who remain in the market will face less competition than at any other time of year.”
Snitker noted that today’s conversations focus less on price and more on how buyers structure a deal.
“Rate buydowns, seller-paid concessions and adjustable-rate loans are all on the negotiating table right now.”
Luxury homes march to their own beat
While most of the market eased off, the $1 million+ segment stepped on the gas.
Year-to-date sales in that tier rose 2% to 4,449, even as overall sales slid 5%.
These homes didn’t linger, either. They spent a median of 21 days on the market in September, compared with 32 days metro-wide.
Luxury condos and townhomes also bucked the broader attached home slump. Their year-to-date closings climbed 6.4%.
“While lower price segments struggle, this segment isn’t waiting for conditions to improve,” said Michelle Schwinghammer, a realtor with West + Main and member of the Denver Metro Association of Realtors trends committee.
“It’s capitalizing on the opportunities already in front of it.”
What comes next?
While the next few months will test September’s rate climb, Snitker isn’t panicking.
“If the market responds the way it has to every other shift over the past four years, the lesson will be the same one it keeps teaching: the opportunities here don’t hinge on rates falling or prices climbing,” she said.
The news and editorial staffs of The Denver Post had no role in this post’s preparation.


